IMF Warns Global Debt Could Hit 100% of GDP Amid Rising Rates
IMF warned that rising interest rates are squeezing public finances and could drive global debt to 100% of GDP by the end of the decade. Speaking at the IMF–World Bank Annual Meetings held in Thailand, Rodrigo Valdés said fiscal positions are deteriorating despite resilient growth and urged countries to rebalance budgets and adopt growth‑friendly tax policies. The Fund also called for targeted energy support and stressed that tax reforms can boost growth without reducing overall revenue.
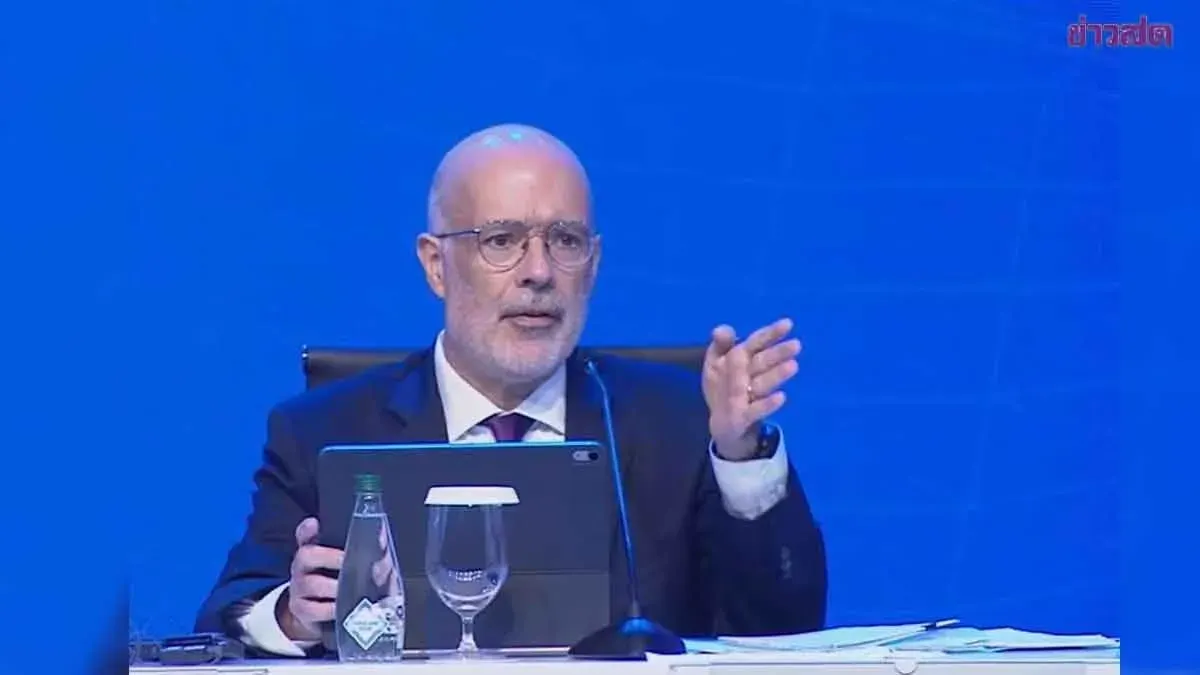
The IMF’s Fiscal Monitor shows global fiscal positions have worsened by about 1.4% of GDP compared with six months earlier, showing that economic growth does not automatically curb deficits or debt. Broad energy subsidies and price controls, costing roughly 1.5% of global GDP, mainly benefit higher‑income groups and fail to curb demand; the Fund urges targeted, temporary support instead. Higher interest rates raise debt‑service costs, making debt stabilization harder, especially when the interest‑rate‑minus‑growth (R‑G) gap narrows. Valdés recommended three steps: streamline taxes and spending to reduce distortions, accelerate fiscal consolidation in high‑debt countries, and address the energy crisis by letting prices reflect scarcity while shielding vulnerable households. He also stressed that tax reforms can boost growth without cutting overall revenue.