Thai Deputy PM Calls for ASEAN Opportunity Amid Economic Storm
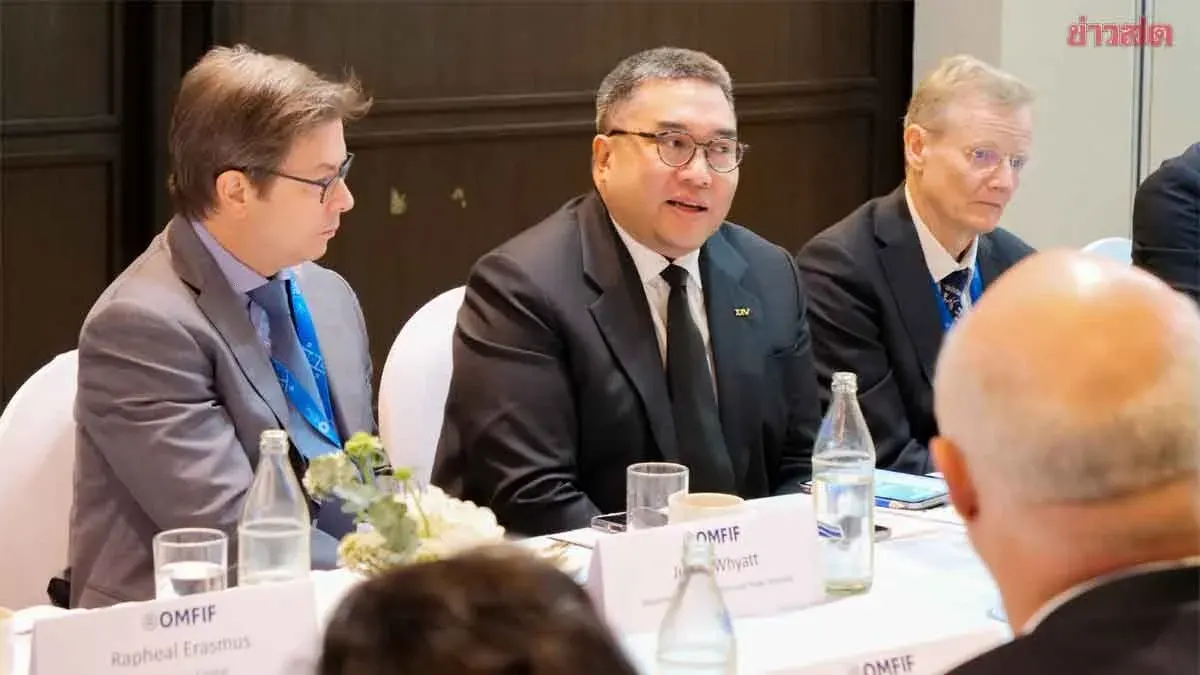
Thailand’s Deputy Prime Minister Ekniti Nitithanprapas warned that the country faces multiple global economic pressures, comparing it to a small boat in a storm, while urging swift action to seize opportunities from ASEAN’s 700‑million‑person market. He called for attracting foreign investment in high‑growth sectors, upgrading skills through the Skill Bridge program, and reducing bureaucratic barriers to keep private investment growing. The goal is to ensure Thai businesses and workers can board the incoming high‑speed train of opportunity and boost national competitiveness.
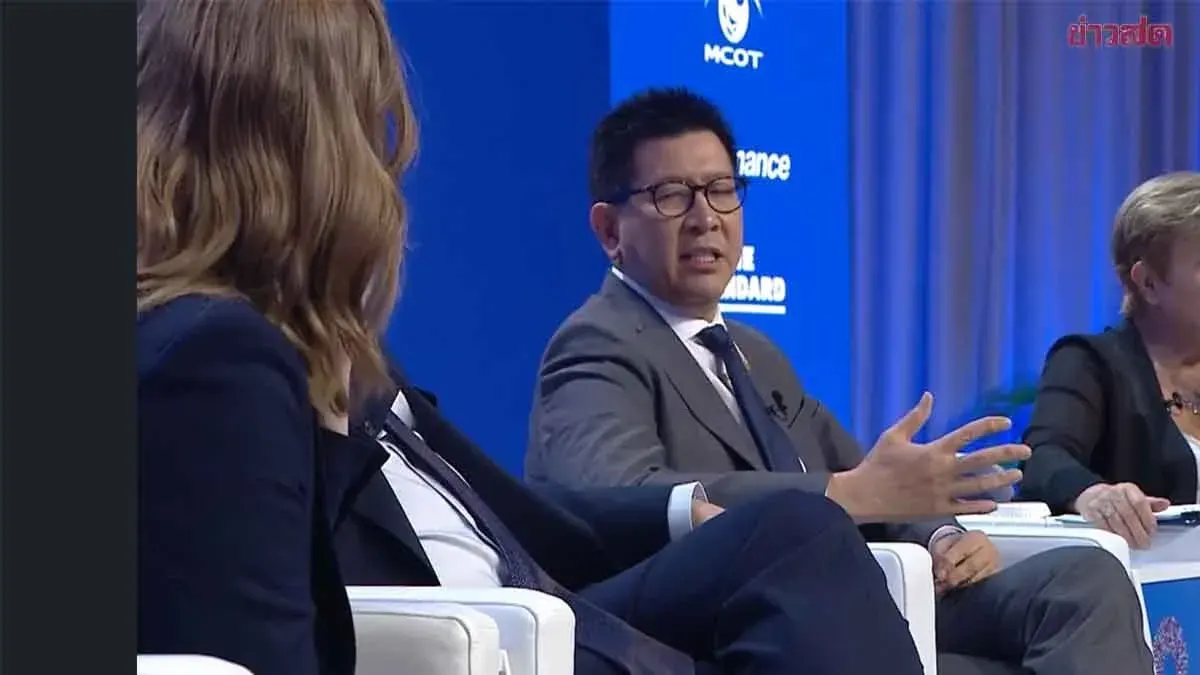
Ekniti Nitithanprapas, Deputy Prime Minister and Finance Minister, addressed the Debate on the Global Economy forum at the 81st annual meeting of the World Bank and IMF, held in Bangkok on October 15, 2026, with Thailand as host at the Queen Sirikit National Convention Centre. He described Thailand as a small boat caught in multiple storms of the global economy, citing rising energy prices, higher interest rates, the spread of artificial intelligence, and growing geopolitical and economic fragmentation. These pressures raise business and household costs, increase financing costs, reshape production methods and skill needs, and force companies to re‑shape supply chains and diversify production sites to reduce uncertainty.
To build resilience, Thailand needs strong, appropriate economic policies that maintain stability, protect vulnerable groups, and help people adapt. Despite the risks, Ekniti noted opportunities from being part of ASEAN, home to about 700 million people, and from global firms seeking alternative production and supply‑chain locations. Thailand must use its infrastructure and investment climate to attract foreign direct investment in future industries such as AI, smart electronics, and future transport, including electric vehicles, ensuring that Thai citizens benefit.
The government is linking foreign investors with workforce development through the Skill Bridge program, which partners with Thai universities to transfer knowledge and teach needed skills for new industries, while also opening supply‑chain roles for small and medium enterprises and local entrepreneurs. Improving regulations and cutting bureaucratic hurdles are also priorities to make doing business easier. Ekniti pointed out that private investment has grown more than 10 percent for two consecutive quarters, using investment as a tool to return the country to a growth path and restructure the economy through structural reforms.
He likened the current opportunity to a high‑speed train arriving in Thailand, with many Thais still standing on the platform; the nation’s mission is to open the doors so that as many Thai people and businesses as possible can board, raising productivity and competitiveness.