Thai Household Debt Hits 17-Year High at 795,000 Baht
Thai household debt has hit a 17-year high of nearly 796,000 baht per household, with weak repayment capacity particularly affecting low-income families struggling with rising living costs and sluggish economic recovery.
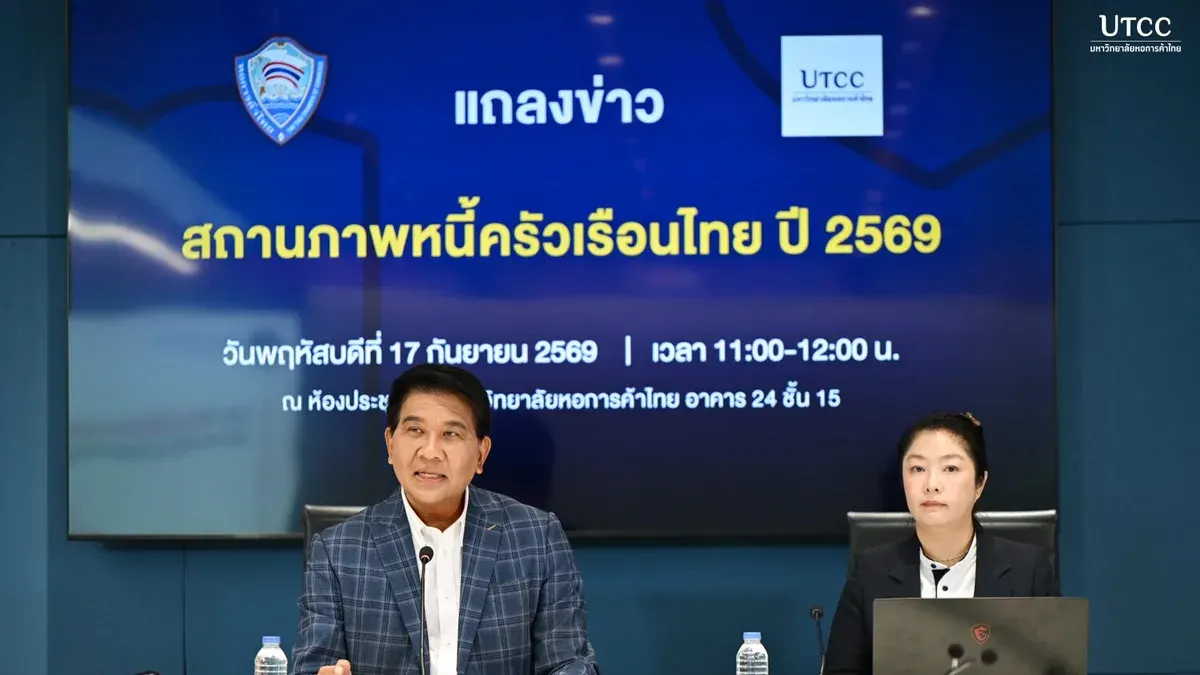
Thai household debt has reached an average of 794,945 baht per household, the highest level since Thai Chamber of Commerce University began tracking the issue 17 years ago, according to research released by university rector Thanvarthan Polwichai. Although the debt-to-GDP ratio is declining, household repayment capacity remains weak, especially for low-income families and those facing high expenses. The survey of 1,720 households nationwide between September 7-13, 2025, found that 91.8% carry debt, down from 95.1% in 2024, while 8.2% are debt-free. Average debt per household increased 7.3% to 794,945 baht from 740,597 baht previously, consisting of 77.2% formal lending and 22.8% informal debt, with average monthly repayment at 21,935 baht, up 8.11% year-on-year.
Creditcard debt remains the most common form at 55.1%, followed by personal consumption loans (45.8%), auto loans (41.9%), business loans (33.6%), and home loans (27.2%). Buy-now-pay-later debt jumped to 14.2% from 6.2% previously. Polwichai noted that the high debt level reflects sluggish economic recovery, with household income and business earnings growing slowly, forcing many to rely on credit for liquidity. Living costs, especially energy, continue to exert pressure.
When asked why debt increased, respondents cited household financial pressures (15.6%), insufficient income (15.5%), rising living costs (14.1%), and unexpected emergencies (11.8%). On repayment capacity, 73.1% reported they can pay on schedule, while 16.1% believe they can clear debt within six months, 8.9% within three months, and 1.9% cannot repay at all. Additionally, 67.5% experienced payment delays or defaults in the past year, primarily due to unexpected expenses (32.2%), reduced income (24.8%), poor economic conditions (21.3%), higher repayments (11.4%), and job loss (10.4%).