Thailand Pushes Early Savings Amid Rapidly Aging Population
Thailand’s Government Pension Fund secretary warned at an IMF-World Bank forum that the country is rapidly aging, with about 20% of the population aged 60 or older, threatening retirees’ financial security. He urged faster savings, long-term investment, and the use of AI to tailor retirement plans, while pushing legal changes to let former members return their funds for continued management. The GPF aims to become a lifetime partner for members, turning retirement savings into sustainable lifelong income.
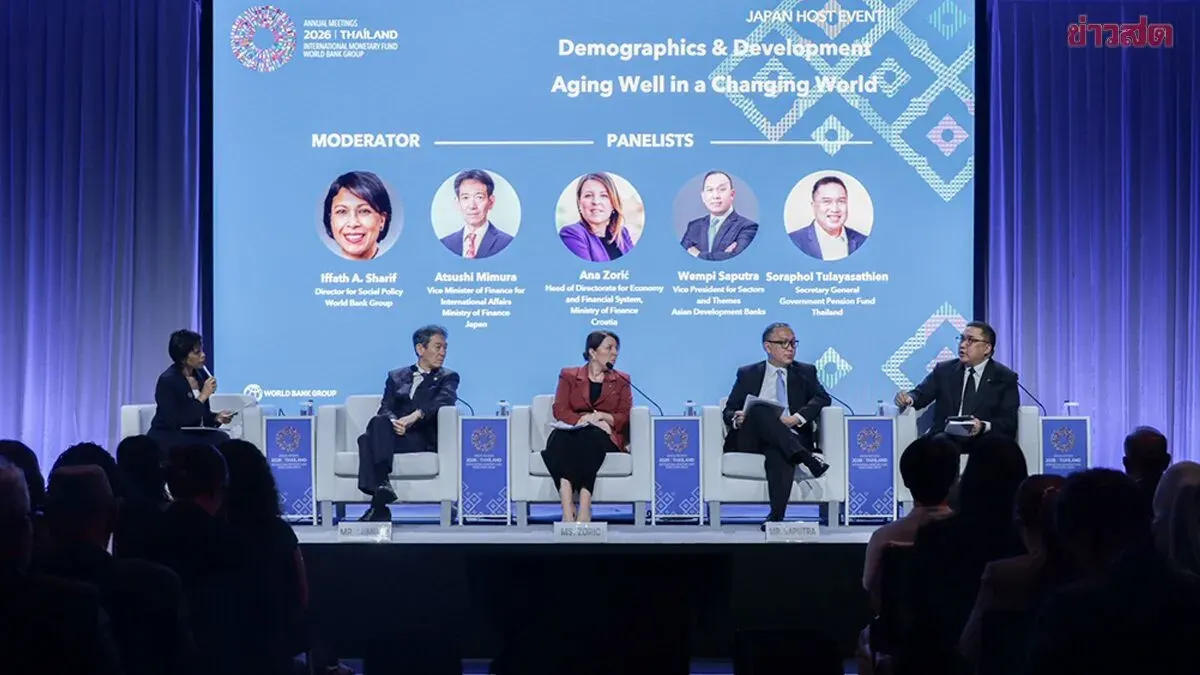
Sorapol Tulayathiti, Secretary-General of the Government Pension Fund (GPF), took part in the IMF-World Bank forum, warning that the world is confronting the challenges of an aging and longer-living population. He urged faster savings and retirement financial planning, noting that the GPF is adjusting its strategy by employing AI to analyze data and design investment plans, while also pushing for legal changes that would allow former members to return their funds for continued management, turning retirement savings into a sustainable lifelong income.
Speaking on the topic "Demographics & Development: Aging Well in a Changing World" at a side event organized by the Japanese government during the 2026 IMF and World Bank annual meetings, he said Thailand is rapidly becoming an aged society, with about 20 percent of the population aged 60 or older, affecting post-retirement financial security and future fiscal burdens. Consequently, promoting long-term saving and investment is essential, especially for the more than 200,000 GPF members who will retire within the next decade.
Addressing demographic shifts requires fostering a longevity society where people can live, work, and participate economically for longer. Many countries entering aged societies must accelerate long-term saving systems from working age, following the principles of saving early, saving enough, and investing appropriately, as time is key to improving future quality of life.
Meanwhile, the GPF aims to enhance member services through data and technology, creating a financial data ecosystem and applying AI to analyze behavior and craft personalized savings and investment plans (segmentation and persona). This aligns with members’ behaviors, financial goals, and risk tolerance, alongside the legal push to let former members return their funds for ongoing management, transforming retirement savings into a lifelong sustainable income.
"The role of the GPF should not end when a member retires from civil service; it should be a lifetime partner throughout the member’s life, keeping savings working and generating continuous returns, providing stable income sufficient to support life as longevity increases," Sorapol said.