Thailand Insurance Regulator Warns of Six Emerging Risks
Thailand's insurance regulator has identified six major risks—economic, demographic, climate, technological, fraud, and geopolitical—that are pressuring the industry. It is pushing to amend laws and strengthen supervision to detect and address these threats early. The initiative aims to protect policyholders and ensure the stability of the insurance sector.
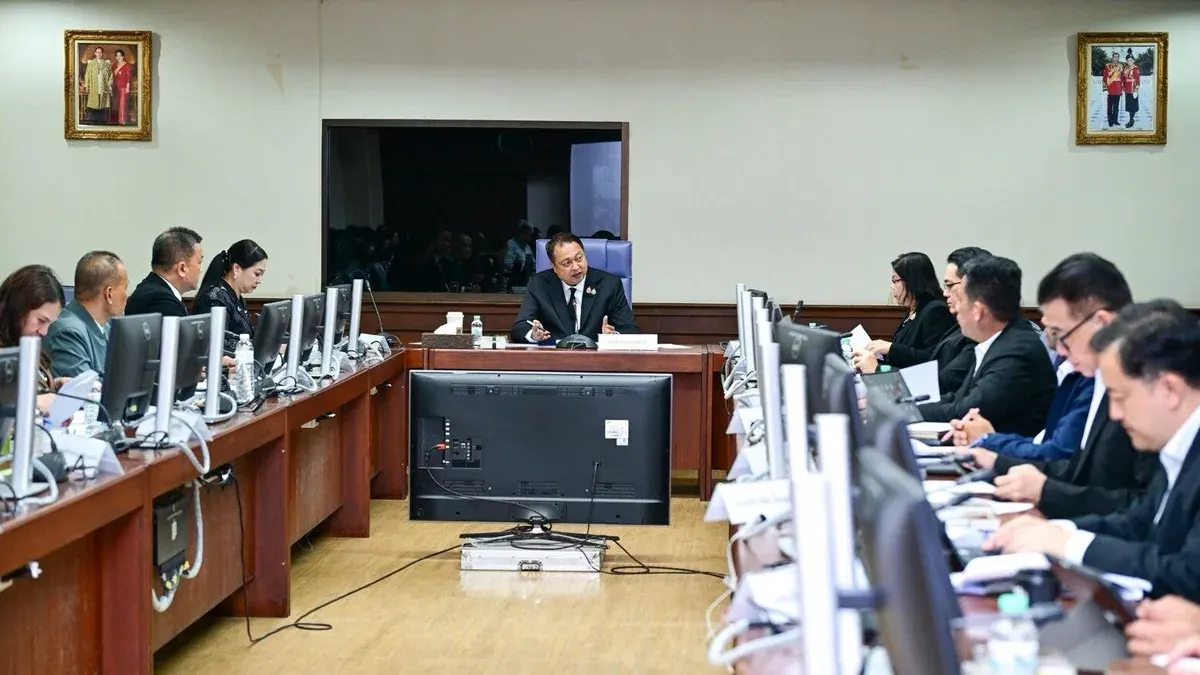
Thai Insurance Commission reveals six risks shaking the insurance sector, urging legal amendments to strengthen it. Chuchat Phanmonpon, Secretary-General of the Thai Insurance Commission (CIC), said the commission is ready to proceed with amendments to the Life Insurance Act and the Non‑Life Insurance Act, particularly the second cluster of laws concerning the stability and soundness of insurance companies, in order to enhance supervision so that risks can be detected and addressed before they cause damage that could affect policyholders. “The aim of this initiative is to prepare for new, more complex and interlinked risks that affect both public demand for protection and the operation of the insurance business.” Chuchat said the world currently faces six major risk areas, or Mega‑Risks, that influence consumer decisions and insurance‑business operations: Economic and financial risk, stemming from slow growth coupled with inflation, household debt, and volatility in financial markets and interest rates, which may force people to choose between debt repayment and maintaining insurance coverage, while insurers face fluctuating investment returns and claim‑cost volatility. Social and demographic risk, arising from an ageing society; by 2040 (2583 BE) elderly people are expected to make up nearly 28 % of the total population, driving up medical costs and demand for pension insurance while the working‑age customer base shrinks. Climate and disaster risk, from floods, storms, wildfires and earthquakes that are becoming more severe—for example, the 2025 Hat Yai floods and the Myanmar earthquake—increasing claim‑payment burdens and reinsurance costs, while the public seeks coverage that enables quick recovery from disasters. Technology and cyber risk, including data leaks, ransomware malware, deep‑fake imagery and audio, and AI‑driven fraud, which pose challenges for insurers that store large amounts of personal and health‑related data. Fraud risk, as AI‑generated fake images, sounds and videos become harder to detect, compelling insurers to develop detection and prediction systems and to strengthen data and transaction security. Geopolitical risk, from international wars and conflicts that affect energy costs, transportation, supply chains, and also marine and aviation insurance businesses. “These growing risks mean insurers must have solid financial positions and capital reserves, together with effective risk‑management systems, to absorb widespread losses without compromising claim payments or obligations to policyholders.” Chuchat added that, regarding the revision of the second‑cluster laws, the CIC office aims to raise supervisory standards to align with domestic conditions and international norms, covering qualifications of senior executives and major shareholders, the independence of key professionals such as actuaries, maintaining capital commensurate with risk levels, as well as data collection and disclosure. It also emphasizes early‑intervention measures when insurers begin to experience problems, so risks can be spotted and remedied before damage occurs, reducing impact on policyholders and the overall stability of the insurance system. The CIC is also pushing to enhance enterprise‑wide risk management (ERM) and the Own Risk and Solvency Assessment (ORSA) for insurers.