Thailand Plans National Disaster Insurance for 30 Million Homes
Thailand's government will launch a national disaster insurance scheme by 2026, automatically covering all 30 million residential properties with 15 billion baht in annual premiums, shifting disaster relief costs from unpredictable governme
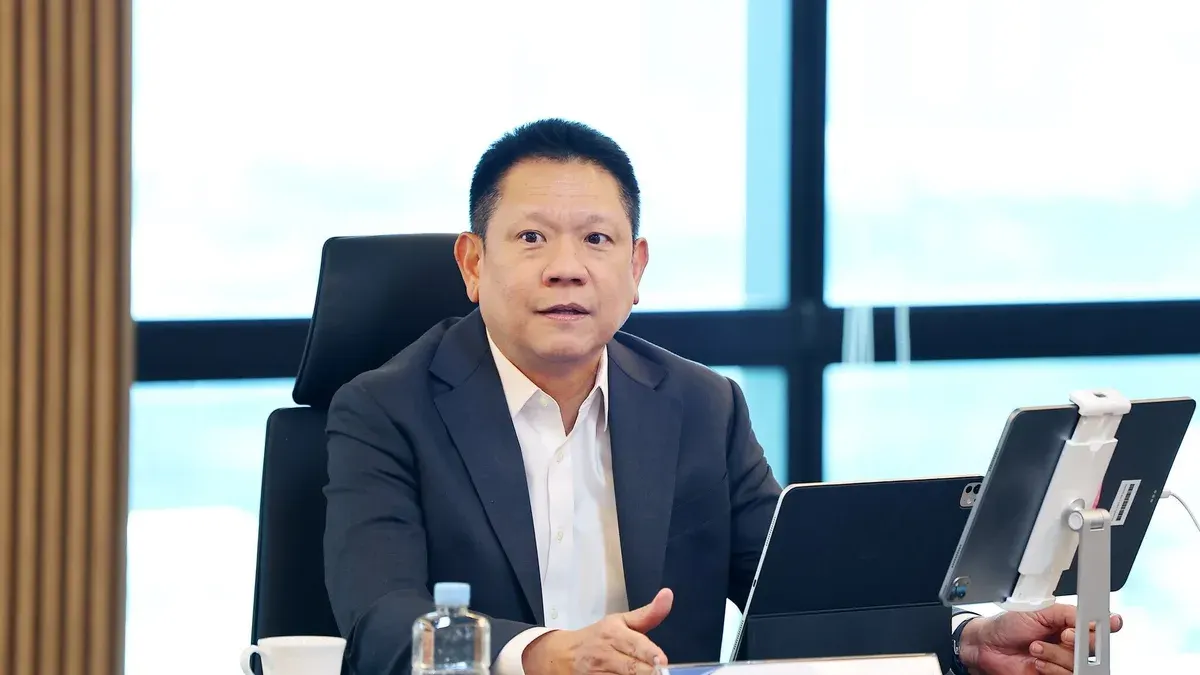
The Finance Ministry is allocating 15 billion baht annually to establish a national disaster insurance scheme providing automatic coverage for all residential properties, estimated at 30 million households. Finance Ministry Permanent Secretary Lueavarun Seansnit revealed that the Cabinet has approved the national disaster insurance programme in principle as an alternative to post-disaster relief. The Finance Ministry and Insurance Commission are coordinating details to launch the system within 2026.
The reform transfers disaster risk management from the government, which historically bears the full burden regardless of annual variation in disaster severity, to an insurance-based mechanism. This approach will improve budget efficiency and maximize value from the state budget, particularly central funds. Under the scheme, the government will insure all residential properties nationwide—currently estimated at 30 million homes—without citizens needing to register or take any action. Every property receives automatic protection.
"The national disaster insurance is a good approach because it removes the unpredictable annual risk the government has carried alone," Lueavarun said. "Risk severity varies year to year, and disasters strike when they occur. The government doesn't know how severe they'll be, yet must allocate budget—central fund money. Under this scheme, the government insures all 30 million homes, and every household qualifies automatically."
Historically, when disasters strike, the government declares disaster zones and uses budget funds for relief. On average, the Disaster Prevention and Mitigation Department spends approximately 30 billion baht annually on disaster compensation. Since severity varies yearly, budgeting and allocation have been difficult.
Under the insurance model, the government will shift to paying annual premiums of approximately 15 billion baht in exchange for coverage protecting against losses up to 75 billion baht—a cost-effective arrangement that stabilizes government budget volatility. Launch is expected within 2026.
When asked how insurers can absorb such large claims, Lueavarun explained that the insurance system evaluates risk over 5–10 years rather than annually, since disaster losses fluctuate—some years severe, others minimal. This creates alternating profit and loss years, making commercial viability feasible. The Thai Non-Life Insurance Association will underwrite the scheme and manage risk through reinsurance abroad, dispersing exposure to international insurance markets rather than concentrating it in Thailand.
"Insurers don't evaluate year by year; they look long-term over 5 or 10 years," he said. "So one year might be severe, another uneventful—profit and loss alternate. Insurers must take the long view, and they also manage reinsurance placement abroad to transfer risk overseas, avoiding concentration in Thailand alone."