Panel Demands Tax Investigation Into Ex-Abbot Over 720 Million Baht Assets
A parliamentary committee demands tax investigation into a former abbot whose foundation seized 720 million baht in assets at a temple in Ayutthaya, citing suspicious gold sales and lack of tax filings despite significant financial activity
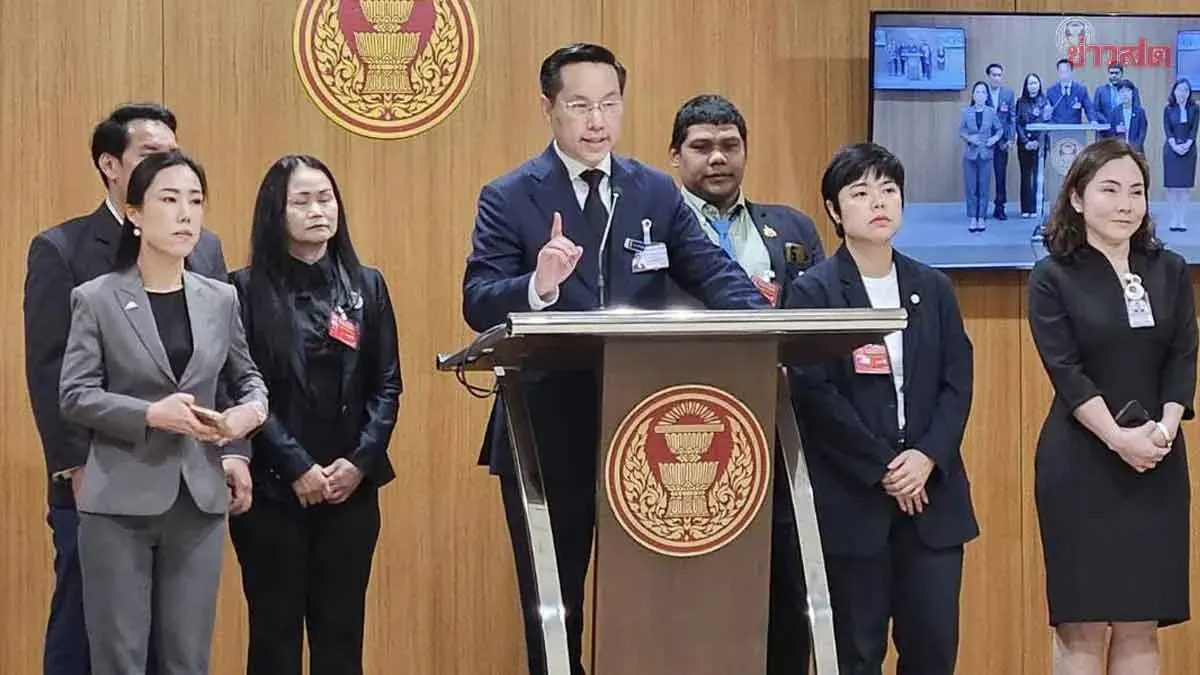
On September 24, Pithakdet Detchdecho, a Nakhon Si Thammarat MP from the Democratic Party and chair of the parliamentary anti-money-laundering committee, announced findings from an investigation into a former abbot of Phuthai Sawan Temple in Phra Nakhon Si Ayutthaya and associates. Seized assets totaled approximately 720 million baht in gold and cash. The temple foundation was registered in 2568 with a capital of 500,000 baht from donations and a monk as chairman, located within the temple grounds. Initial inquiry found no irregular or unlawful activity.
Expenditure records showed purchases of gold for religious items, medical equipment, and jasmine rice in compliance with civil and commercial law. However, the committee found it suspicious that Buddha amulets were sold under the foundation's name while certification documents were issued in the temple's name. Detchdecho said authorities have been asked to verify whether this constitutes a legal violation.
Former abbot Atchoti faces criminal charges of embezzlement and fraud. The Ayutthaya monastic leadership confirmed a temporary abbot was appointed to oversee the temple following the incident. The temple has nine accounts with monthly financial reports and multiple donation channels including QR Code, operating under ministerial regulations and monastic council resolutions.
The Bank of Thailand confirmed it monitors customer accounts under anti-money-laundering measures and found no violations so far, pending further reports. Detchdecho remarked the central bank should work faster and not wait for reports. The Revenue Department noted the foundation has a tax identification number but found no record of any tax filing from the foundation or individuals involved. Tax obligations apply regardless, and must be assessed case by case based on income type and circumstances.